

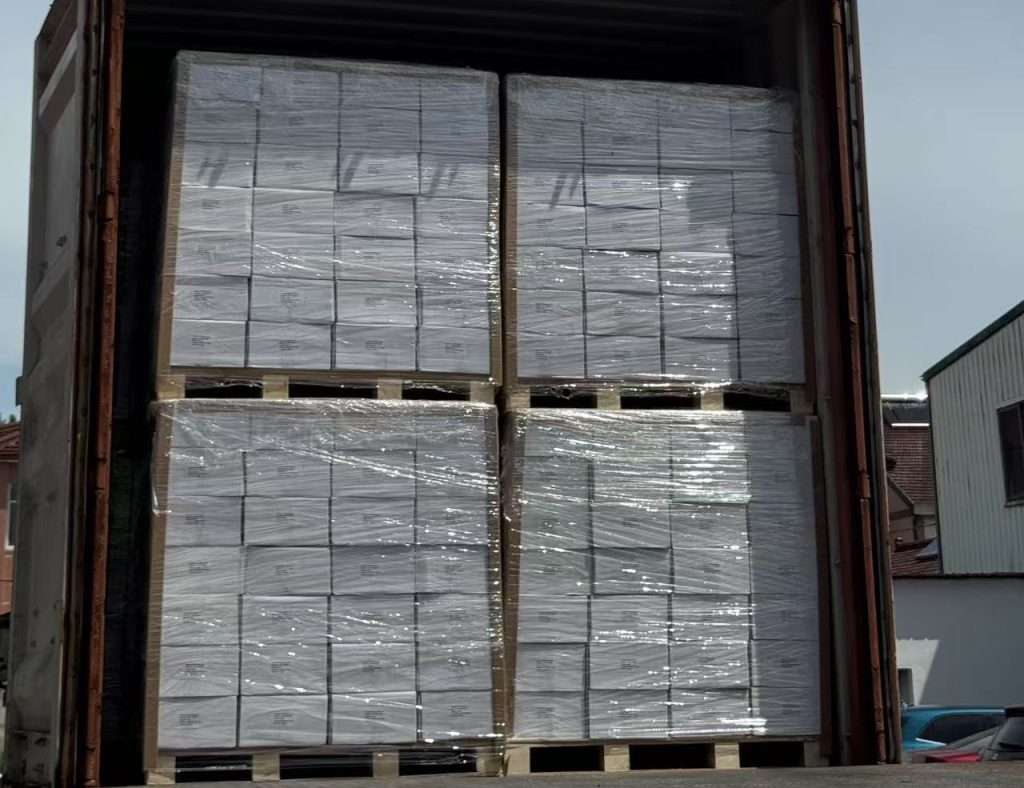
A first-time importer gets a quote: $22 per square meter FOB China for a standard AB-grade European Oak engineered hardwood, 15mm thick with a 3mm wear layer. They add what looks like a reasonable buffer for shipping and assume the landed cost will be around $25–$27. Three months later the container clears US customs and the actual landed cost is $36 — about 60% above the FOB price. The math wasn’t wrong on shipping. It was wrong on tariffs.
This is the most common failure point in the engineered wood flooring cost stack. Not retail markup, not distributor margin — the silent compounding of import duties, anti-dumping cash deposits, and freight surcharges that turn a $22 plank into $36 before it ever reaches a wholesaler.
This breakdown follows the price layer by layer with verifiable 2026 numbers from public market data — Made-in-China FOB listings, Federal Register tariff filings, freight rate indices, and US retail pricing. No factory-specific quotes; just the structure of the trade as it actually works.
The Five Cost Layers Between Factory and Retail
Every engineered hardwood plank passes through five cost layers between the mill and the homeowner’s living room. Each is run by people who need to make money, which is what compounds the price.
| Layer | Who absorbs it | Typical cost added | Cumulative cost (per m²) |
|---|---|---|---|
| 1. Factory cost (FOB China) | Produttore | $18–$30/m² base | $18–$30 |
| 2. Landed cost | Importer | +$10–$20/m² | $28–$50 |
| 3. Wholesale to distributor | Distributor | +22–30% margin | $34–$65 |
| 4. Retail markup | Retailer | +37–55% margin | $47–$100+ (materials only) |
| 5. Installation labor | Contractor | +$32–$86/m² | $79–$186+ installed |
The cumulative numbers shift dramatically based on three things: the spec of the floor, the route it takes (direct-to-retailer vs. through a distributor), and the destination market’s tariff regime. A standard AB-grade Oak engineered with a 3mm wear layer follows a different cost curve than a wide-plank European Oak with a 4mm wear layer, even though both can call themselves “European Oak engineered” on the label.
The next sections walk each layer with the specific drivers — and the points where importers, distributors, and contractors most often misjudge the math.
Layer 1: Factory Cost (FOB China) — $18–$30/m²
FOB stands for Free On Board: the price you pay with the goods loaded onto the vessel at the export port, with everything from production to local trucking included. It’s the cleanest baseline for comparing one factory to another.
Public Made-in-China listings from real engineered hardwood factories (not SPC or laminate sellers using “engineered wood” in their listing titles for SEO) show the following typical FOB price bands for 2026:
| Product type | FOB China (per m²) |
|---|---|
| Entry-level Oak engineered, AB grade, 14mm/2mm wear layer, 125mm narrow plank | $15–$20 |
| Standard Oak engineered, AB grade, 15mm/3mm wear layer, 190mm plank | $20–$25 |
| Wide plank Oak engineered, 15mm/3mm or 4mm wear layer, 220–300mm plank | $25–$30 |
| Wide plank with sliced/dry-sawn veneer, premium finish | $28–$35 |
| Chevron / herringbone Oak engineered | $20–$30 |
A common warning sign for first-time buyers: when a quote comes back at $5–$8/m² for “engineered oak,” the product is almost always SPC or laminate flooring with an oak-grain top film, not real engineered hardwood. Real European Oak engineered with any meaningful wear layer cannot be produced and exported below roughly $15/m² without compromising the wood, the core, or both.
Inside the FOB number, the major cost drivers — in the order they impact unit economics — are:
Wear layer veneer. This is the single biggest variable on the price sheet. A 4mm wear layer costs the factory roughly 35–45% more in raw material than a 2mm layer, because the veneer log yields fewer slices. On a 1,000 m² order, the difference between 2mm and 4mm at FOB level is several thousand dollars. This is also the easiest spec for a factory to quietly downgrade to win a price-sensitive bid.
Core construction. A premium 11-ply eucalyptus and birch crossband core costs more than a 3-ply poplar core, even though both can be sold as “engineered.” The premium core resists humidity-driven movement; the cheap core warps. Buyers who only ask “is it engineered” without specifying the core composition are letting the factory pick the cheaper option.
Finish system. A multi-coat UV-cured lacquer system from Treffert, Klumpp, or Bona Industrial adds $1.50–$3.00/m² over a basic 3-coat finish. A WOCA hard wax oil system adds similar. These are real costs; cheaper finishes wear through faster, generating warranty claims that show up later in the chain.
Plank dimensions. Wider planks waste more veneer at the edges of each log. Longer planks require longer kilns and more selective grading. Both push FOB cost up, sometimes by 20–30% over a standard 1,200 × 125mm plank.
Grade. Prime grade (no knots, uniform color) costs more than Rustic (visible character marks) — not because it’s better wood, but because the factory had to discard more boards to assemble each pack. The price gap between Prime and Character grade in the same species is typically 15–25% at FOB.
Two specs that look identical on a brochure can have a 60% difference in factory cost. This is why the most expensive line on a quote sheet is usually the one without enough detail.
Layer 2: Importer Landed Cost — Add $10–$20/m²
This is the layer that catches first-time importers. “Landed cost” is what a container actually costs by the time it sits in your warehouse, ready to sell. The math has more line items than most quotes prepare you for, and the largest line — tariffs — is in active flux through 2026.
| Cost line | Typical range (per m², 1,000 m² container) | Note |
|---|---|---|
| Sea freight (FOB → US/EU port) | $1.40–$2.20 | Based on $1,400–$2,200 per 20’GP, 1,000 m² load |
| Cargo insurance | $0.10–$0.25 | ~0.3–0.7% of cargo value |
| Combined US import duties | $6–$15 | See breakdown below |
| Customs broker + entry fees | $0.10–$0.25 | Per-shipment fixed cost spread over the container |
| CARB/TSCA test verification | $0.05–$0.15 | If retesting at port |
| Port handling, drayage, demurrage | $0.40–$0.80 | Higher in peak season |
| Domestic trucking to warehouse | $0.50–$1.20 | Distance-driven |
| Warehouse + carry cost | $0.30–$0.60 | Until inventory turns |
| Total added | $10–$20 |
A 20-foot container is the standard for engineered hardwood — not because of volume, but because of weight. Engineered hardwood is dense; a 20’GP loaded to its volume capacity exceeds the weight limit of most shipping lanes. Factories typically load 20’GPs to 1,000–1,200 m² of 15mm flooring. Trying to use a 40HQ for a single SKU usually triggers carrier overweight surcharges.
The Tariff Stack Importers Underestimate
US tariffs on Chinese-origin engineered wood flooring are not one number. They are a stack, and several of the layers are subject to ongoing administrative reviews and new investigations through 2026. As of early 2026, the layers that may apply to a single shipment include:
- Base HTS duty (Chapter 4412): typically 0–8%, depending on the specific HTS subcode and species
- Section 301 List 3 tariff: 25% additional, in effect since 2018 and confirmed extended through 2026
- Antidumping duty (AD) on multilayered wood flooring from China: Order in effect since December 2011. Most recent CIT decision lowered the rate for non-individually-examined exporters from 42.57% to 31.63%. Producer-specific rates vary widely — some have rates near 0%, others well above 30%.
- Countervailing duty (CVD) on multilayered wood flooring from China: Same 2011 order. Producer-specific rates from near 0% to 8%+.
- New AD/CVD investigation on hardwood and decorative plywood from China (initiated June 2025, preliminary affirmative determinations January–March 2026): potentially adds another cash deposit layer for entries after June 2025 if final determinations affirm.
- Section 232 tariffs on wood products (October 2025 proclamation): currently does not apply to plywood under HTS 4412, but the Commerce Department has a report due October 2026 that may extend tariffs to additional wood categories.
Combined, the realistic total tariff load on Chinese-origin engineered wood flooring in 2026 sits in the 30–65% range depending on the producer, the HTS classification, the importer’s record-of-entry date, and which AD/CVD orders apply. This is wide because it is genuinely uncertain — an exporter with a low individually-examined AD rate will land in the 30–35% range; an importer using a Chinese exporter assigned the country-wide rate could face 60%+.
The practical implications:
- Always classify the HTS code with a customs broker before quoting a customer. A 1% misclassification difference on the HTS code can move a shipment between categories with very different AD/CVD treatment.
- Verify your supplier’s AD/CVD cash deposit rate before placing the order. Suppliers can provide their assigned rate from US Department of Commerce records.
- Build a tariff buffer into landed cost projections. Tariff rates can change between order date and entry date due to ongoing administrative reviews.
For European importers, the tariff structure is fundamentally different — typically a base CN duty without the Section 301 component, though anti-dumping investigations have applied at various times and similar verification with a local broker is essential.
For the documentation side of the import workflow, our China sourcing guide covers the bills of lading, fumigation certs, and Lacey Act declarations needed to clear customs without demurrage.
Layer 3: Wholesale to Distributor — Add 22–30%
Distributors exist because the math of small-quantity trucking, sampling, sales support, and customer service does not work at the importer level. A distributor takes the importer’s landed inventory and breaks it into smaller shipments for retailers and contractors who can’t or won’t buy by the container.
According to industry research published by Floor Daily, the operating cost of a hard-surface flooring distributor runs around 22% of sales — selling, sampling, logistics, training, returns. On top of that, distributors need profit margin to stay in business, which puts a typical distributor markup at 22–30% over their cost.
So a $36/m² landed import becomes a $44–$47/m² wholesale price to the retailer.
A few patterns at this layer worth knowing:
The “direct-to-retailer” pitch is partial. Some manufacturers sell direct to large retail chains, skipping distributors entirely. This works when the retail account is large enough to absorb logistics and service costs that a distributor normally provides. Industry data from Floor Daily shows only Shaw and Mohawk operate direct distribution at meaningful scale in residential hard surface. For everyone else, distributors handle the last mile. If a small importer is being sold on “direct to dealer” margins, the question is who is absorbing the service costs the distributor would normally absorb.
Volume tiering happens here. Large distributors with multi-container annual volume often negotiate FOB or landed prices that are 8–12% below smaller distributors. This is the source of the price disparity that smaller dealers see between “what my distributor charges me” and “what big-box retailers seem to pay.”
Sampling is a hidden cost. A distributor’s average annual cost to service one specialty flooring retailer is roughly $26,000 across servicing, sampling, and support, according to Floor Daily research. Distributors recover this through markup, which explains why distributor pricing on niche or low-velocity SKUs is often disproportionately high — slow movers don’t generate enough volume to absorb their share of service costs.
Layer 4: Retail Markup — 37–55%
Retailers convert wholesale inventory into individually purchasable square footage. They also absorb the cost of physical showrooms, sales staff, advertising, sample books, returns, and customer credit. Retail margins reflect that overhead.
Industry-wide, the average retail flooring margin is 37%, per Bizminer data published by QPro. Inside that average:
- Commercial projects: <30% margin
- Builder/apartment work: 30–35% margin
- Residential remodel: >40% margin (often 45–55% on hardwood specifically)
Retailer pricing software vendors like HomeArize report that hardwood gets 45–55% markup as a category default — higher than carpet (28–38%) or LVT (38–48%) — because hardwood requires more sample inventory, more knowledgeable staff, and longer customer decision cycles.
The visible result of these stacked margins is the price you see at retail in 2026:
| Retail tier | Engineered hardwood materials only |
|---|---|
| Big-box (Home Depot, Lowe’s, Menards) | $32–$65/m² ($3–$6/sq ft) |
| Online direct (Flooring.org, BuildDirect) | $43–$108/m² — typically 20–40% below traditional retail |
| Specialty flooring stores | $54–$172/m² ($5–$16/sq ft) |
| LL Flooring / Bellawood mid-tier | $43–$90/m² |
These numbers cover a wide spec range. The bottom of each band is typically a 2mm wear layer, narrow plank. The top is a 4mm wear layer, wide European or American oak with premium finish. The relationship between wholesale cost and retail price is not constant across that range; retailers tend to apply percentage markup, so absolute margin grows with spec.
For a deeper view of how retailers position hardwood inside the broader flooring market, our 12 types of flooring guide covers comparable category pricing.
Layer 5: Installation — Add $32–$86/m²
Installation is not a cost of the product, but it’s the line that converts retail material price into the number the homeowner actually writes a check for. For engineered hardwood, professional installation in 2026 runs $3–$8/sq ft according to HomeGuide and Homewyse — that’s $32–$86/m² on top of materials.
What drives the variation:
Installation method. Floating click-lock installations are the cheapest, often at the bottom of the labor range, because they require no adhesive, fasteners, or specialty tools. Glue-down over concrete adds $1–$2/m² in adhesive cost plus more skilled labor, pushing labor to the middle of the range. Nail-down requires a wood subfloor and a flooring nailer, sitting near the top. For more on choosing a method, see our glue down vs floating vs nail down comparison.
Subfloor preparation. A flat, dry, clean subfloor adds nothing. A subfloor that needs leveling can add $11–$22/m². A subfloor with moisture issues that requires a vapor barrier system can add another $11–$22/m² in materials and labor combined. These are the line items that turn “the install was $5/sq ft” into a final invoice that’s 30% higher.
Pattern complexity. Standard plank installation is the baseline. Diagonal installation adds 10–15% in waste and labor. Herringbone or chevron patterns can add 25–40% in labor due to the time required to lay each board precisely.
Region. Urban labor rates in major US metros run $6–$10/sq ft. Rural rates run $3–$5/sq ft. The same installation is twice as expensive in San Francisco as it is in central Ohio.
The Math: A 1,000 m² Order, From Factory to Front Door
The cost layers above are abstract until you walk a real order through them. Here is a representative mid-market spec — a standard AB-grade European Oak engineered, 15mm total thickness with a 3mm wear layer, 190mm wide plank, UV lacquer finish — followed across the full chain at 2026 prices.
| Stage | Cost per m² | Cumulative | Multiple of FOB |
|---|---|---|---|
| FOB China (factory loaded onto vessel) | $22 | $22 | 1.0× |
| Sea freight to US West Coast | +$1.80 | $23.80 | 1.08× |
| Cargo insurance + customs broker | +$0.30 | $24.10 | 1.10× |
| US tariffs (assume mid-range 45% combined) | +$9.90 | $34.00 | 1.55× |
| Port + drayage + trucking + warehouse | +$2.00 | $36.00 | 1.64× |
| Importer landed cost | $36.00 | 1.64× | |
| Distributor markup (~25%) | +$9.00 | $45.00 | 2.05× |
| Wholesale to retailer | $45.00 | 2.05× | |
| Retail markup (~50% specialty store) | +$22.50 | $67.50 | 3.07× |
| Retail materials price | $67.50 ($6.27/sq ft) | 3.07× | |
| Installation labor (mid-range glue-down) | +$54.00 | $121.50 | 5.52× |
| Final installed price to homeowner | $121.50 ($11.30/sq ft) | 5.52× |
A few things worth pulling out of this table:
The factory captures roughly 18% of the final installed consumer spend. Tariffs and freight together are 11%. Distribution is 7%. Retail markup is 19%. Installation labor is 45%. Everyone along the chain has a real cost basis to defend.
The biggest single jump happens at the import layer. From the FOB price of $22 to the landed cost of $36, the importer has absorbed a 64% increase — and most of it is tariffs, not freight. This is the layer where first-time importers most underestimate their costs, because freight rates are easy to look up but the tariff stack is buried in Federal Register filings most importers never read.
The retail markup is large in absolute dollars ($22.50/m²) but only 50% of wholesale. People often assume retail markup is the biggest layer; in truth it’s roughly the same as the tariff burden.
If the same importer chose Vietnam, Indonesia, or a non-China origin, the landed cost would shift meaningfully because the AD/CVD orders specifically target China. That does not mean other origins are automatically cheaper — Vietnam and Indonesia are also under active AD/CVD investigations as of 2026 — but the tariff math is different and worth running for any spec.
What Drives the Biggest Cost Variation: 5 Spec Choices
Two products both labeled “Oak engineered hardwood” can have a 60% price gap at the FOB stage alone, which compounds through every later layer. Five spec choices, in order of impact:
1. Wear layer thickness. A 2mm wear layer adds the lowest FOB cost; a 4mm wear layer can add 35–45% to the FOB price for the same plank size. The functional difference is refinishing potential: a 4mm wear layer can be sanded and refinished 2–3 times over its life, a 2mm wear layer cannot be refinished at all. For a 25-year residential floor, the 4mm wear layer is usually the better lifetime value despite the higher upfront cost.
2. Core composition. Eucalyptus and birch crossband cores cost more than poplar. The premium ranges from $1–$3/m² at FOB level depending on origin. Eucalyptus and birch resist humidity-driven movement; poplar warps under the same conditions. Buyers who optimize on FOB price by accepting a poplar core often pay for it later in warranty claims and customer satisfaction issues.
3. Finish system. A multi-coat UV-cured finish from a recognized supplier (Treffert, Klumpp, Bona Industrial) adds $1.50–$3.00/m² over a generic finish. UV-cured commercial-grade systems can add another $2–$4/m². The finish is also the most visible quality marker — a cheap finish looks plastic and wears unevenly within 5 years.
4. Plank dimensions. A standard 1,200 × 125mm plank is the cheapest format because it makes efficient use of veneer. A 1,900 × 220mm wide plank can cost 25–35% more at FOB for the same wood and finish, because wider boards mean more selective grading and more waste at the log edges.
5. Grade. Prime grade (clean, uniform) costs 15–25% more than Character grade (visible knots, color variation), even though Character grade is no less durable. The cost difference is yield: more boards have to be sorted to assemble Prime grade packs.
Stack the wrong choices on each axis and the FOB price doubles. Stack them right for your end market and you can hit your spec at the bottom of the price band.
For the technical specifications side of this — what to actually write into a PO so the factory can’t substitute cheaper components — see our QC and inspection checklist for importers.
From the Factory: Where Buyers Overpay (and Underpay)
Three patterns we see consistently across importer orders, where the cost-quality math goes wrong in both directions.
Overpaying for a wear layer that isn’t there. A buyer pays a 30% premium for “4mm wear layer” boards that, when measured on a cross-section cut, run 2.5–2.8mm. The wear layer is invisible from the top surface, so the only verification is destructive testing — which most buyers never do. The fix is including a calipered cross-section measurement in pre-shipment QC, with a tolerance of ±0.2mm. Without that test, “4mm” is a label, not a spec.
Saving money on the core, paying for it in claims. A buyer takes a $2/m² discount for a poplar core instead of eucalyptus-birch. On a 1,000 m² container that’s $2,000 saved at FOB. Six months after delivery, 8% of the boards show cupping when ambient humidity rises. Replacement, freight, and reputational cost on a single bad batch routinely exceeds $20,000. The economics of cutting core spec almost never work, but they look attractive on a quote comparison.
Missing the MOQ-driven cost cliff. First-time importers ask for 200 m² of a custom finish. The factory’s minimum custom production run is typically 700 m² per color, sometimes 2,000 m² for private label. Below that floor, the factory runs the order anyway but prices it 25–40% higher to cover the inefficient setup. Buyers don’t understand why the price is so high and assume the factory is profiteering. The real fix is consolidating SKUs to hit the MOQ, or accepting standard finishes for first orders. Our private label manufacturer guide covers MOQ economics in more detail.
The pattern across all three is the same: the right cost decision needs both the FOB number and the spec verification framework around it. Either alone is incomplete.
FAQ
How much does engineered wood flooring cost per square meter wholesale from China?
Standard AB-grade Oak engineered with a 3mm wear layer typically runs $20–$25 per square meter FOB China for orders of 1,000 m² or more, based on 2026 Made-in-China public listings from real engineered hardwood factories. Wide plank or 4mm wear layer specs run $25–$30/m². Below 500 m² total order, expect a 15–25% small-order surcharge. Quotes below $10/m² for “engineered oak” almost always indicate SPC or laminate flooring with an oak-grain top film, not real engineered hardwood.
What’s the difference between FOB and CIF pricing?
FOB (Free On Board) covers production and local transport to the export port; the buyer arranges and pays for ocean freight, insurance, and import clearance. CIF (Cost, Insurance, Freight) bundles the freight and insurance into the supplier’s price. FOB gives the buyer more control over routing, freight forwarder choice, and timing — most experienced importers prefer FOB once they have a reliable forwarder. CIF is simpler for first-time buyers but typically includes a 5–10% markup on freight versus arranging it directly.
How much do US tariffs add to the cost of Chinese engineered wood flooring?
The realistic combined tariff load in 2026 is in the 30–65% range, depending on the producer’s specific AD/CVD cash deposit rate, the HTS classification, and which orders apply to your shipment. The stack includes a base HTS duty (typically 0–8%), Section 301 List 3 tariffs (25%), antidumping duties on multilayered wood flooring from China (most recently 31.63% for non-individually-examined exporters per a 2025 CIT decision), countervailing duties (varies by producer), and potentially new AD/CVD measures from a 2025 hardwood plywood investigation pending final determination. Always verify current rates with a licensed customs broker before quoting a customer — tariff schedules change frequently as administrative reviews are decided.
Why does chevron flooring sometimes cost the same as wide plank?
Chevron and herringbone patterns require precise 45-degree or 60-degree angle cuts, tighter dimensional tolerances at the joints, and more veneer waste at cut angles. Pattern flooring also needs more selective milling. The combination typically prices chevron at $20–$30/m² FOB — overlapping with wide plank pricing rather than running multiples above it. Where chevron really costs more is at the installation layer, where labor adds 25–40% over standard plank.
What’s the typical retail markup on engineered hardwood?
Industry-wide retail flooring margins average 37% per Bizminer data, but hardwood specifically runs 45–55% in residential markets. Specialty flooring retailers and design showrooms tend to be at the higher end; big-box retailers like Home Depot and Lowe’s run lower margins on volume SKUs but compensate through higher overall sales velocity.
Can I save money by buying direct from a Chinese manufacturer?
Direct-from-factory works when your annual volume justifies the logistics, sampling, and customer-service infrastructure that a distributor would otherwise provide. For most first-time importers under 5 containers per year, the math favors working with a distributor or going through a manufacturer that handles import logistics on the buyer’s behalf. Direct factory pricing is 22–30% lower than distributor wholesale — but only if you can absorb the operational cost yourself.
What’s the minimum order quantity for custom engineered wood flooring?
Custom production (specific color, finish, or grade) typically requires 700 m² per SKU at most factories. Private-label runs (custom branding, packaging, labels) usually need 2,000 m² per SKU. Below those minimums, factories will quote the order but at 25–40% above standard pricing to cover setup costs.
Get a Real Quote, Not a Range
Public market data gives you the structure of the trade. It doesn’t give you a price for your specific spec, your destination market, your order volume, or your timeline. Two buyers asking for “Oak engineered hardwood, 3mm wear layer” can receive quotes that differ by 25% based on order quantity, finish system, and shipping window — before tariffs add another 30–65% on top.
If you’re sizing a project or evaluating supplier quotes against the structure above, request a custom quote with your specs and we’ll send a line-itemed FOB price covering wear layer, core, finish, dimensions, and grade — with the math broken out so you can see which choices are driving the number.


 Italian
 English
 French
 German
 Russian
 Spanish
 Chinese
 Korean
 Japanese
 Turkish